Europe Revises Sustainability Reporting Standards
In recent years, the European Union (EU) has gradually strengthened its regulatory framework for sustainability disclosures to enhance corporate transparency and provide investors and other stakeholders with information to assess sustainability-related risks, impacts, and opportunities.
One of the key foundations of this framework is the Corporate Sustainability Reporting Directive (CSRD), which requires companies within its scope to report in accordance with the European Sustainability Reporting Standards (ESRS). The standards cover environmental, social, and governance (ESG) issues, including climate change, biodiversity, human rights, and workforce-related matters.
However, implementation has also presented challenges regarding the volume of information that companies must collect, process, and disclose. To address these challenges, the EU has introduced the Omnibus I simplification package, which aims to reduce administrative burdens and adjust the scope of companies subject to mandatory reporting requirements.
As part of this initiative, on 3 July 2026, the European Commission (EC) adopted the revised ESRS and established a voluntary reporting standard for companies outside the scope of mandatory reporting. The two regulations were subsequently published in the Official Journal of the European Union on 21 September 2026.
According to the European Commission, these adjustments aim to maintain the quality of disclosed information while making sustainability reporting more concise, clearer, and better aligned with companies' actual capabilities.
ESRS: Significantly Reducing Disclosure Data Points and Increasing Flexibility
One of the most notable changes to the ESRS is the streamlining of the number of data points companies are required to disclose. According to the European Commission, mandatory data points have been reduced by more than 60%, while the total number of data points has decreased by more than 70%. The Commission also expects these changes to reduce reporting costs by more than 30% per company.
In addition to reducing the number of data points, the revised standards have been designed to be shorter and clearer, with greater flexibility and simplified implementation procedures.
Key areas of adjustment include:
Streamlining disclosure requirements: Reducing the number of mandatory data points and removing optional data points that are no longer necessary, thereby limiting the amount of information companies need to collect.
Clarifying materiality requirements: Providing more specific guidance on identifying material information, helping companies focus on sustainability issues that are genuinely significant to their operations and stakeholders.
Prioritizing quantitative data: Shifting towards greater use of quantitative indicators rather than relying excessively on descriptive information, thereby improving the assessment and comparability of disclosed information.
Increasing flexibility: Introducing support mechanisms and adjusting implementation timelines for certain requirements, giving companies more time and flexibility to prepare their data and reporting systems.
Importantly, simplifying the ESRS does not mean abandoning the core objectives of sustainability reporting. Environmental, social, and governance issues remain central to the standards. Companies are still required to identify material impacts, risks, and opportunities related to their operations in order to provide relevant information.
The revised standards will apply to financial years beginning on or after 1 January 2027. For the 2026 financial year, companies in the relevant reporting groups may choose to apply either the existing standards or the revised standards, subject to the applicable transitional provisions.
VS and VSME: A Voluntary Reporting Approach for Businesses with Fewer Than 1,000 Employees
Alongside the revision of the ESRS, the EU has also established the Voluntary Sustainability Reporting Standard (VS), targeting companies outside the scope of mandatory sustainability reporting with fewer than 1,000 employees.
The VS builds on the VSME (Voluntary Sustainability Reporting Standard for SMEs) recommendation developed by the European Financial Reporting Advisory Group (EFRAG). However, the two concepts should be distinguished. The VSME is a standard developed by EFRAG and recommended by the European Commission in 2025, whereas the VS is a voluntary standard established by the EC through a legal act in 2026, building on the VSME framework and adapting it to the new regulatory context.
Unlike the ESRS, which applies to mandatory reporting by companies within the scope of the CSRD, the VS provides a more proportionate reference framework suited to the capabilities and resources of smaller businesses. It does not impose mandatory reporting obligations on companies that choose to use it voluntarily.
The VS has three main objectives:
Helping companies provide sustainability information when requested by larger business partners in their value chains.
Addressing the information needs of banks, investors, and financial institutions, thereby supporting companies in accessing financing
Helping companies better identify and manage sustainability issues in their operations, such as environmental pollution, occupational health, and workplace safety.
Another important provision is the Value Chain Cap mechanism. Under this mechanism, companies subject to mandatory reporting under the CSRD cannot require value-chain companies with no more than 1,000 employees to provide information exceeding the limits established under the VS when such information is requested for sustainability reporting purposes under EU regulations.
This mechanism is particularly relevant to small and medium-sized enterprises (SMEs), as even those outside the scope of mandatory reporting may still receive requests for ESG data from customers, major business partners, or financial institutions.
The VS officially entered into force on 24 September 2026. The Value Chain Cap mechanism will apply to financial years beginning on or after 1 January 2027.
What Should Vietnamese Businesses Consider in Response to These Changes?
The EU's revisions do not only concern companies headquartered in Europe. They may also affect foreign businesses participating in European supply chains, particularly suppliers of goods and services to European partners.
For Vietnamese businesses, the extent of the impact will depend on their size, position within the value chain, business relationships with customers, and information requirements from their partners. Companies should not assume that all of them are directly required to apply the ESRS. However, being outside the scope of mandatory reporting does not mean they can disregard ESG considerations.
As European partners continue to seek environmental, social, and governance information, ESG data may become an increasingly important part of business assessments and the maintenance of commercial relationships.
The establishment of the VS provides a reference framework for smaller businesses to standardize the information they provide to their partners. However, the Value Chain Cap does not mean that businesses are exempt from all data disclosure requests. This limitation applies specifically to information requested for sustainability reporting purposes under the relevant EU regulations and does not replace other information obligations arising from different legal requirements or legitimate purposes.
In light of these changes, Vietnamese businesses should focus on several key areas:
First, review the scope and reporting requirements. Businesses should determine whether they fall within the scope of mandatory reporting and identify the standards used by their customers, business partners, and financial institutions to assess ESG information.
Second, establish a consistent ESG data management system. Information on energy consumption, greenhouse gas emissions, water use, waste, working conditions, and governance should be systematically collected, stored, and updated. Data should have clear sources, consistent calculation methodologies, and be verifiable when necessary.
Third, identify material sustainability issues. Rather than collecting data indiscriminately, businesses should assess the issues that have significant impacts on their operations, business activities, and stakeholders. This also provides a basis for selecting relevant information for sustainability reporting.
Fourth, select an appropriate reporting framework. Businesses need to distinguish between the ESRS, VS, and VSME to determine the approach best suited to their size, capabilities, and information disclosure needs. The choice of reporting standard should not be driven solely by market trends but should reflect actual market and business partner requirements.
Overall, the EU's efforts to simplify sustainability reporting standards create more favorable conditions for businesses to engage in sustainability disclosure. However, these changes do not diminish the importance of ESG data in corporate management and supply chain relationships. Early preparation will help businesses adapt more effectively to market developments and reduce pressure when requests for information arise.
GREEN IN Hosts a Webinar on the Latest Changes to ESG Reporting in Europe
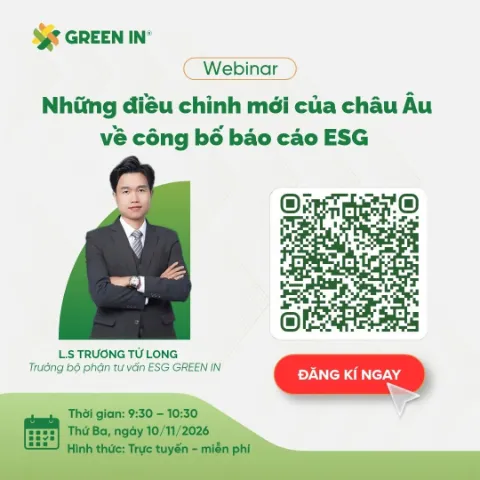
To help businesses stay informed about changes to Europe's sustainability reporting framework, GREEN IN is organizing a webinar entitled "New European Adjustments to ESG Reporting and Disclosure."
The webinar will focus on the latest developments in the ESRS and VS, the differences between VS and VSME, the implications for Vietnamese businesses, and the preparations needed for ESG data and reporting systems.
Webinar details:
Time: 9:30–11:00 AM, 10 November 2026 (meeting room opens at 9:15 AM).
Format: Online via Zoom.
Fee: Free of charge.
Speaker: Lawyer Truong Tu Long – Head of ESG Consulting Department, GREEN IN.
References
- 1. GREEN IN ↗ (accessed 2026-11-06)
- 2. European Commission – Commission adopts revised sustainability reporting standards ↗ (accessed 2026-11-06)
- 3. EFRAG – European Commission adopts revised ESRS and VS ↗ (accessed 2026-11-06)
- 4. European Commission – Commission Delegated Regulation (EU) 2026/1560 ↗ (accessed 2026-11-06)
- 5. European Commission – Commission Delegated Regulation (EU) 2026/1563 ↗ (accessed 2026-11-06)
- 6. European Commission – Questions and Answers on the Voluntary Sustainability Reporting Standard for SMEs (VSME) ↗ (accessed 2026-11-06)